September 21, 2026
Adapting to structural forces, navigating uncertainty
Governor Tiff Macklem discusses how businesses and households are adapting to the long-term forces reshaping the Canadian economy.
Good afternoon. It’s a pleasure to be here in Halifax. I’d like to thank the Halifax Partnership for the invitation and all of you for joining us today.
In February, I gave a speech about structural change—the profound economic adjustment facing Canada and the world. I highlighted increased trade tensions, rapid advances in artificial intelligence (AI), and demographic changes that were beginning to reshape our economy.
Six months later, there’s mounting evidence that Canadian businesses and households are adapting to those forces, and the economy is growing once again. Businesses are adjusting their supply chains, exploring new markets, investing in new technologies and hiring new workers. As a result, the economy began the summer in a stronger position. Exports, investment and growth all picked up, and conditions in the labour market began to improve.
But two important developments are shifting the risks to growth and inflation.
Trade tensions between Canada and the United States have re-escalated, creating fresh uncertainty for businesses and households. And the conflict in the Middle East has persisted longer than many expected, pushing oil prices up further.
Today I want to talk about how businesses and households have been adapting to structural forces and what that has meant for the Canadian economy. Then I’ll discuss recent developments—both their near-term impact on growth and inflation, and the risks to the outlook. Finally, I’ll explain how the Bank of Canada is thinking about these risks as we work to keep inflation low, stable and predictable for Canadians.
I don’t think it’s an exaggeration to say that Canada has gone through several stages of grief over the death of open trade with the United States. We’ve moved through some combination of shock, denial and anger to coping and responding.
Businesses are facing a similar adjustment process as they confront major structural forces. Broadly speaking, I see three stages.
First, businesses reassess. They need to understand what has changed and what it means for them. How big is the shock? Will it intensify or fade? How will it affect demand, costs and competitiveness? In this initial stage, they’re asking questions more than taking action—and that pause in decision-making can slow economic growth. That’s part of the reason why the economy stalled in 2025 and early 2026.
The second stage is adapting. Businesses start making practical adjustments. They look for new suppliers and new ways to meet customer needs. They experiment with new tools and technologies. These changes can happen relatively quickly. They are often reversible, and they can get production and growth moving again.
But while adaptation restores activity, the third stage—transformative change—is what raises productivity and expands the economy’s capacity to grow without creating inflationary pressures. Businesses develop new products and invest in new technologies and markets. Workers move into expanding industries. Governments help workers transition and support growth by building infrastructure and easing regulatory burdens. All these decisions take longer and are harder to reverse. But they are essential to higher incomes, improved affordability and greater resilience over the long run.
I want to focus for a few minutes on the second stage—adaptation—because this is where we’ve begun to see more evidence that Canadian businesses and households are responding to the current challenges. And that has helped the economy recover.
I’ll start with how businesses are adapting to the shift in the Canada-US trade relationship.
Since the trade conflict began in 2025, businesses have had to navigate tariffs, retaliatory measures and a lot of unpredictability. Canada’s auto, steel and aluminum sectors have been particularly hard hit, and the recent breakdown of negotiations extended steep tariffs to yet more businesses.
But there is growing evidence that many Canadian businesses have started to adapt. Non-energy exports rose 14½% in the second quarter—reaching their highest level since early 2025. And the gains were broad-based across export categories. While some temporary factors boosted quarterly growth, our surveys and outreach suggest the rebound reflected deliberate business decisions. Businesses are reducing their exposure to tariffs. They’re adjusting supply chains and they’re changing sourcing strategies.
Exporters are also looking beyond the United States. For most, that has so far meant expanding relationships with existing overseas customers rather than entering new markets. Diversification is not easy. And our geography suggests the United States will remain Canada’s largest trading partner. But Canadian businesses are building resilience by broadening their options.
The labour market tells a similar story. While sectors reliant on exports to the United States have had it tougher than others, through 2025 businesses slowed hiring plans rather than cut jobs.1 So far this year, private sector hiring has strengthened, and the unemployment rate has edged down.
The second force reshaping Canada’s economy is artificial intelligence. Businesses see AI as a way to improve service, reduce costs and increase productivity. As firms adapt to AI, most are not transforming their business overnight. They’re using AI to automate routine tasks and work more efficiently. Most are still in the early stages of experimenting with AI. It will take time for bigger productivity gains to materialize as businesses integrate AI tools and redesign their processes.
Adoption is spreading quickly. Statistics Canada reported in the spring of 2026 that almost one in five Canadian businesses had used AI to produce goods or deliver services in the previous 12 months. That’s roughly triple the share reported two years earlier.
For their part, workers are increasingly using AI tools in their jobs. Most are using AI to write, plan and analyze information, freeing up time to focus on higher-value work. But many worry that instead of helping them, AI could replace them.
We’re also seeing businesses adjust their hiring. But those adopting AI tend to change the skills they look for rather than reduce their head count. While we’re not seeing broad-based job losses, recent data show job-finding rates have fallen in occupations that are more exposed to AI.2 As my colleague Deputy Governor Michelle Alexopoulos noted earlier this year, past waves of innovation have generally created more jobs than they eliminated.3 But that doesn’t mean the transitions are easy.
A third force reshaping the economic landscape is demographic change. Slower population growth and an aging population are changing labour supply and consumer demand. The Bank expects that growth in the labour force—the number of people working or looking for work—will be close to zero over the next few years.
So how do we cope with all this? Adaptation is a start. But raising productivity ultimately depends on investment and transformative change. Despite the uncertainty we’re facing, business investment rose at an annualized rate of 8.8% in the second quarter. Businesses tell us they are looking for ways to improve productivity, integrate AI and broaden their customer base. More than two-thirds of Canadian exporters say they plan to expand into new markets over the next two years, with many now looking beyond the United States to Europe and the Asia-Pacific. That points to something more fundamental than adaptation alone.
Governments have an important role to play. They help create the conditions for businesses to invest, innovate and grow. They can also help workers in disrupted industries develop new skills and move into expanding sectors of the economy. They can reduce licensing and permitting barriers. We’re already seeing greater emphasis on energy systems and transportation networks to improve how goods move within Canada and beyond. Efforts are underway to strengthen Canada’s internal market and reduce some of the many barriers to trade within the country. And new trade agreements will open additional markets for Canadian exporters.
These investments will take time to bear fruit. But over time, they will expand the economy’s productive capacity.
Taken together, these developments suggest the economy entered the summer in a stronger position. Growth had resumed, investment was picking up and companies were beginning to look beyond the headwinds to opportunity.
But now, two important developments are clouding the outlook.
The first is the breakdown in trade negotiations and the imposition of new tariffs.
The second is the persistence of the conflict in the Middle East.
How much these affect the economy will depend on how events unfold and how Canadians adapt.
If these new US tariffs remain in place, they will hit affected sectors hard. There is no question about that. But when we look at the overall economy, we don’t expect a large direct effect. The affected products represent about 5% of Canada’s goods exports to the United States, and federal government support programs should mitigate some of the harm.
But the unpredictability of US trade policy has increased uncertainty for everyone. Businesses have spent the past year adapting to higher tariffs. And now the situation is changing again. The latest escalation could once again cause businesses to delay investment and hiring decisions—pushing some businesses back to the reassessment stage. This would set back the progress we’ve seen and restrain growth. And because a weaker economy puts downward pressure on inflation, it would affect the inflation outlook as well.
If these new tariffs remain in place, growth could be roughly halved in the fourth quarter, to below 1%.
The conflict in the Middle East presents a different challenge.
Back in July, when we released our Monetary Policy Report, the conflict was expected to ease and supply disruptions to gradually normalize. Instead, key shipping routes remain disrupted and refineries have been damaged.
Under normal circumstances, every 10% increase in oil prices adds about 0.2% to consumer price index (CPI) inflation. But this time, the effects go beyond the price of crude oil alone. Damage to global refining capacity has pushed up the costs of gasoline and diesel further. As a result, fuel prices have risen more than we’d normally expect given the increase in oil prices. In fact, recent gasoline prices have been more consistent with an oil price almost US$40 higher than where it has been.
Canadians see the consequences of that every time they pass a gas station. Businesses see it in elevated transportation and distribution costs. And for the economy as a whole, it’s keeping inflation higher than we expected.
CPI inflation has remained around 3% in recent months, largely because of these higher fuel prices. As things stand now, if oil prices stay near $100 per barrel, we would expect inflation to edge up in the coming months.
The Bank has been looking through the direct impact of higher oil prices on inflation because so far, we haven’t seen a lot of evidence that these higher costs are spreading to other goods and services. But we’re watching closely. With the conflict ongoing and shipments from the Middle East still curtailed, the risk that inflation broadens and becomes more persistent has increased.
In addition, Canadian counter-tariffs could add costs for some businesses and eventually feed into consumer prices. The counter-tariffs primarily target non-consumer goods that can be replaced with Canadian substitutes. As a result, we expect their impact on inflation will be modest.
We’re also seeing the Middle East conflict being reflected in global financial markets. Several factors are pushing bond yields higher. Governments and businesses have increased borrowing, which pushes up longer-term yields. At the same time, higher oil prices and inflation mean markets are increasingly expecting major central banks to raise their policy rates. That’s pushing up short-term yields. While Canadian yields remain below those in the United States, bond yields have risen here too.
Taken together, these developments are pulling the economy in different directions. Trade uncertainty will weigh on demand. Higher energy prices will keep inflation up. One creates downside risks to growth, while the other creates upside risks to inflation.
And both arrive at a time when many Canadians are still seeing the effects of past price increases. Even though inflation was around the 2% target for more than a year before the war drove up energy prices, the prices of most goods and services did not come down. That has left many feeling an affordability squeeze. We hear it in our conversations with Canadians across the country.
That brings me to the Bank’s role and how we’re assessing the impact of these developments on growth and inflation.
We can do the math. Higher oil prices mean higher gasoline prices. Together with elevated refinery margins, that will push headline inflation higher than we expected a few months ago—much of this is already locked in. We can also estimate the direct effects of tariffs on growth and prices.
But because monetary policy works with a lag, we need to look beyond the immediate arithmetic. Will these effects prove temporary or persistent? Do higher energy prices raise inflation for just a few more months? Or does inflation stay too high, requiring us to raise our policy interest rate to contain it? How much will new US trade actions and increased uncertainty weigh on growth and employment? And how much will that dampen inflationary pressure?
To answer these questions, we need to look beyond the initial shock.
Higher energy prices don’t just affect what Canadians pay at the pump. They also raise costs for businesses. Those businesses then have to decide whether to absorb those costs or pass them on. And if they pass them on, will those price increases spread more broadly through the economy, fuelling ongoing inflation? Will higher inflation push up households’ longer-term inflation expectations, making it easier for businesses to continue to raise prices? How businesses and households respond will influence how inflation evolves beyond the next few months.
Growth and inflation in the quarters ahead will also depend on Canada-US trade relations. There are sound economic reasons for the United States to reduce tariffs and restore certainty. The integrated production processes that link our two economies have benefited both countries—indeed, Canada is the leading export market for a majority of US states. Canadian counter-tariffs are not in place because Canada wants an escalating trade conflict. They are there to encourage a return to lower tariffs with our most important trade partner.
It’s unlikely that Canada and the United States will return to the trade relationship that existed two years ago. But there are clear economic incentives on both sides of the border to reduce barriers and uncertainty.
Until that happens, uncertainty will weigh on investment and hiring decisions. How businesses and households respond will be an important determinant of growth. Even with the recent rebound, the economy remains in excess supply. And if growth weakens once again for several quarters, economic slack will persist, making it harder for businesses to raise prices.
Our job is to assess where inflation is going and determine where interest rates need to be to guide inflation back to our 2% target. That means distinguishing between cyclical forces that affect demand in the short term and structural forces that change how the economy works over the longer term. It means understanding which inflationary pressures are temporary, and which are likely to last.
That’s why I and my colleagues on Governing Council meet regularly with businesses, workers and community leaders across the country. These conversations—like the ones I’ll be having here in Halifax—help us understand how economic developments are affecting decisions on the ground.
It’s also why we are investing in new analytical tools. We’ve developed a new forecasting model called Prima to help us distinguish between temporary inflation pressures and those that could prove more persistent. It also improves our ability to consider alternative economic scenarios. We will use it for the first time as our primary forecast model for our October Monetary Policy Report.
Earlier this month, Governing Council decided to leave the policy rate unchanged. We noted that inflation and growth in Canada had unfolded broadly as expected over the summer. The rebound in economic activity as businesses adapted to structural forces had put the economy on a better footing. We also noted that developments in the Middle East and the breakdown in trade negotiations with the United States had both increased the upside risk to inflation and made Canada’s growth prospects more uncertain.
Monetary policy cannot offset the effects of tariffs or influence global energy prices. What it can do is ensure that global developments do not jeopardize price stability in Canada. Our beacon is our 2% inflation target, and we are committed to keeping inflation close to target over time. As these risks evolve, we are prepared to adjust monetary policy as needed.
Let me conclude.
Six months ago, I spoke about the structural forces reshaping Canada’s economy. Today, those forces are even more apparent. Over the past year, businesses and households have adapted to profound change. Their response has helped strengthen the economy.
But the outlook has once again become more uncertain. Higher global oil prices and a shortage of refining capacity will keep inflation elevated in the next few months, while the escalation in trade uncertainty will likely dampen growth. The more difficult question is how persistent the inflationary and disinflationary forces will be.
We will be assessing whether the current policy rate balances the risks to our inflation outlook. We don’t want to raise our policy rate and restrain growth if inflationary pressures are contained. But nor do we want to be too slow to respond if inflationary pressures are becoming more persistent.
Uncertainty makes decisions harder. But as we have seen over the past year, businesses are adapting. And so are we. We are consulting more with Canadian businesses and households. And we are improving our economic models to better capture supply disturbances and manage uncertainty.
We are all operating in a world where structural change, geopolitical fragmentation and supply disruptions are becoming more common.
Through all of this, the Bank’s objective has not changed. We remain focused on keeping inflation low, stable and predictable. In an uncertain world, that’s one of the most important contributions we can make to the economic well-being of all Canadians.
Thank you.
I would like to thank Daniel de Munnik, Erik Ens, Patrick Rizzetto and Walter Steingress for their help in preparing this speech.
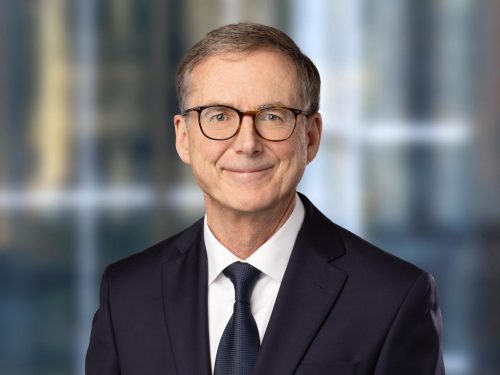
Economic developments — Governor Tiff Macklem speaks before the Halifax Partnership (11:20 (ET) approx.).
Economic developments — Governor Tiff Macklem takes questions from reporters following his remarks (12:30 (ET) approx.)
We use cookies to help us keep improving this website.