Good morning. It’s great to be here in Edmonton. I’d like to thank the Edmonton Chamber of Commerce for inviting me to speak today.

As business leaders, you spend a lot of time thinking about the future. You weigh what’s happening in your business today, consider what might come next and make decisions accordingly.

Of course, the future is uncertain. You have a best estimate of what will happen, but you also need to be prepared for what could happen.

So you think through different scenarios. You ask what-if questions. What if demand for my product spikes? What if diesel prices stay high? What if I have to raise my prices?

Central banks are no different.

Changes to our policy interest rate take time to work their way through the economy. So when setting policy today, we need to be looking ahead.

We forecast a most likely path for growth and inflation, or our base-case projection. But that outlook is conditional on how things unfold. So we also think through the risks that could push inflation off course, the what-ifs.

This is how we make decisions aimed at keeping inflation low, stable and predictable.

But making those decisions is only part of the job. We also need to communicate the thinking behind them. That means explaining how we see the economy today, where we think it might be headed and what data could change that view. Communication, in other words, is an essential part of how we conduct monetary policy.

The challenge is talking about the economy’s future when the future is uncertain.

How should central banks talk about that uncertainty? And how do we make it clear that our projected path for growth and inflation, and any policy guidance we provide, are conditional on the economy evolving largely as expected?

Those questions are at the heart of an ongoing debate around central bank communications.

So today, I’ll begin by looking at how the Bank of Canada’s monetary policy communications have evolved over the past few decades and how they help us keep inflation close to the 2% target.

Then I’ll talk about communicating in times of heightened uncertainty. In those moments, it’s especially important to be clear about what we know and what we don’t know. This is where our what-if scenarios come in.

When uncertainty is extremely high, such as during the pandemic, scenarios can help put a range on possible outcomes. By laying out different paths for the economy and inflation, we can talk about the future even when we can’t be confident about a base-case projection. Scenarios show Canadians how we’re thinking through the uncertainty.

Scenarios can also help when we have a base-case projection. They help us understand how shocks or risks, if they materialize, could derail things. Put another way, they allow us to test our base case against other possible outcomes. And that helps us make more robust monetary policy decisions.

Scenarios have long been part of our internal analysis at the Bank. What’s changed is that we’re now publishing them more often. This shift has been driven by a rise in uncertainty. We’re living in a more shock-prone world. Scenarios can help us show how economic shocks could affect the economy and inflation, and what that could mean for our policy response.

I’ll wrap things up by connecting the dots between communication, accountability and credibility. And I’ll explain how these support the Bank’s operational independence.

Let’s get started.
Why central banks talk

One of the clearest trends in modern central banking has been the move toward communicating more with the public. Collectively, we’ve gone from “If I seem unduly clear to you, you must have misunderstood what I said”1 to “The better Canadians understand our goals, the more likely we are to achieve them.”2

But why have we done this? One reason is to shape policy rate expectations.

We publish forecasts, explain what data we’re watching and identify the risks or potential shocks that matter most for our decisions. As new economic data arrive and economic conditions evolve, we update our forecasts and reassess the risks we’re watching.

All this helps market participants understand what drives the evolution of our outlook and how we might react with our policy rate—what economists call our reaction function.3 In a sense, we want market participants to be able to interpret new information much like we do and, in turn, anticipate how monetary policy might react.

When our reaction function is well understood, monetary policy works better.

Let me explain. At the Bank, we directly control only the target for the overnight rate, also known as our policy interest rate. But households and businesses tend to make their spending, saving and investment decisions based on longer-term interest rates, which are influenced by market expectations about where our policy rate is headed.

By helping market participants understand how we tend to react when economic conditions change, we can shape their expectations. In that way, our communications can influence longer-term rates and, ultimately, economic growth and inflation.

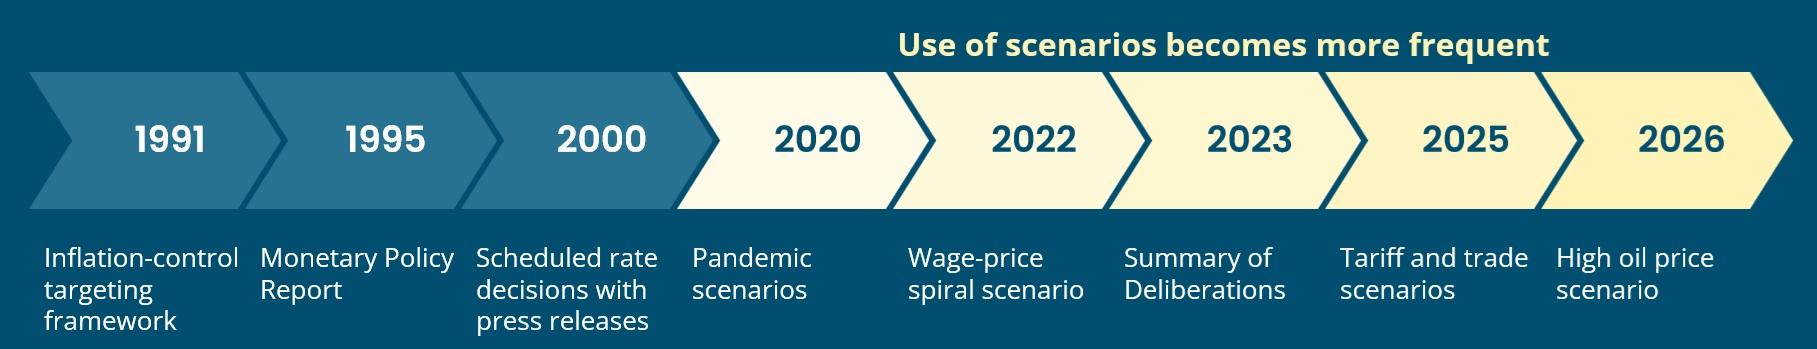
The Bank’s focus on monetary policy communications is not new. It began in earnest in 1991, with the adoption of inflation targeting. Setting a target for inflation created a visible benchmark, and that made accountability much more concrete. For the first time, the public could easily judge success.

Since then, we’ve made a lot of changes to improve our communications (Figure 1).

One of the biggest was the introduction of the Monetary Policy Report (MPR), which sets out Governing Council’s base-case projection, or most likely path, for growth and inflation.

But unexpected developments can hit the economy, throwing inflation off its projected course. This is why the MPR also includes an assessment of the main risks to the outlook for inflation.

We also began giving more speeches like this one. We moved to fixed dates for policy rate decisions4 and began issuing press releases with each one. And, in 2023, we started publishing a summary of deliberations.

These innovations give Canadians more insight into how we weigh the evidence and reach our decisions.5

Figure 1: The Bank’s communications tools have evolved over time

Innovations that have increased transparency

Guidance, not a map

I hope I’ve made the case that central banks can use their communications to help shape policy rate expectations and make monetary policy more effective.

But central banks can also shape these expectations more directly by signalling where policy rates may be headed. This is known as forward guidance.

There are two main types of forward guidance: extraordinary and routine. Extraordinary forward guidance is only ever used in times of crisis when interest rates are at their lowest possible level.6

Routine forward guidance is more common. It can be a statement, such as “We expect interest rates will need to rise further,” or it can be a communication tool, such as a policy rate path.

It’s the use of routine forward guidance—and the publication of policy rate paths, in particular—that is at the heart of the long-running debate I mentioned at the start of my remarks.

Central banks talk about the future a lot. Some see forward guidance as a natural extension of communications, a way of helping market participants understand their reaction functions. But others worry that forward guidance can be taken as a commitment rather than as a conditional signal.

In essence, the debate is about how explicit guidance should be on where the policy rate is going, particularly when the future is uncertain.

Forward guidance can make it easier for markets to anticipate monetary policy decisions. But if markets focus too much on what central banks are signalling, they may pay less attention to incoming data and how that data could affect policy decisions. In a sense, they stop doing their homework.7

If this happens, markets become less of an independent source of information for central banks and more of a reflection of what they are saying.8 As a result, central banks can lose an important source of information about how investors view the economy.

Scenarios can help by reinforcing the conditional nature of forward guidance. In other words, they help make it clear that policy guidance is not necessarily what will happen, but rather what could happen.

The rise of the scenario

I’d like you to think, for a moment, about what the world has gone through over the past few years. A global pandemic and widespread economic shutdowns, followed by a surge in inflation. A war in Europe, a war in the Middle East and an energy price shock. And a trade conflict that has hit Canada particularly hard.

All those shocks have generated a lot of economic uncertainty.

While uncertainty itself isn’t new, the tools used by central banks to communicate it have evolved. I’ll break these tools down into three broad categories.

First, there are confidence intervals, known as fan charts because of how they look. Fan charts capture the uncertainty inherent in any forecast in a visual way. The further out the projection goes, the wider the fan becomes, reflecting how uncertainty grows over time.9

Second, uncertainties can be expressed qualitatively or with words. Important, specific risks are often identified in a stand-alone section of a forecast document, such as the Risks section in our MPR.

And finally, we have the what-if scenarios, which are a natural evolution of these qualitative risk discussions. Rather than simply identifying a risk, they quantify what could happen to the economic outlook if that risk were to materialize. This has made them an increasingly popular tool among central banks.

Given how many shocks the economy has faced in the past few years, you won’t be surprised to hear that the Bank is publishing scenarios more frequently. We generally publish scenarios that explore two types of uncertainty—uncertainty around how an event will play out and uncertainty around how households and businesses will react to that event.

The pandemic, the shift in US trade policy and the recent oil price shock are all examples of the first type of uncertainty. Sometimes, the degree of uncertainty is so extreme that the past is not a reliable guide to what comes next. Economists call this Knightian uncertainty.10 The clearest example is from the early days of the COVID-19 pandemic.

Seemingly overnight, everything shut down. The situation was so unprecedented that we couldn’t feasibly identify a most likely path for growth and inflation. But we didn’t let that uncertainty paralyze us. Instead of a base-case projection, we considered what-if scenarios (Chart 1).

These scenarios helped us establish a range around possible outcomes, which gave the public a rough sense of how the pandemic might affect the economy over time. We hoped that by being clear about the knowns and unknowns, we would enhance our credibility with Canadians. Our goal was to be a trusted voice in a very difficult time.

Publishing scenarios instead of a base-case forecast is something we only ever consider in times of extreme, or Knightian, uncertainty. Most of the time, we publish scenarios alongside the base case because they help us communicate distinct risks to the outlook, such as the economic consequences of behaviour changes. This gets to that second type of uncertainty I mentioned, around how households and businesses could react to a shock.

A good example is from the post-pandemic period. Inflation had risen sharply and was well above target. While longer-term inflation expectations were anchored around 2%, we couldn’t be certain they’d stay anchored. So we turned to a what-if scenario.

In the wage-price spiral scenario that we published in the July 2022 MPR, businesses keep raising prices because they expect inflation to stay high. Workers demand higher wages to keep up, adding to businesses’ costs. This leads to further price increases. Prices, wages and inflation expectations feed off each other, pushing inflation higher still.

The scenario showed that breaking the cycle requires much higher policy interest rates, which leads to a deep recession (Chart 2). This is essentially what happened in the early 1980s.

Fortunately, this scenario didn’t come to pass in 2022. But it illustrated how changes to households’ and businesses’ expectations and behaviour could make high inflation much harder to bring down. And it helped us explain to Canadians the risk we were trying to avoid and why we had to raise the policy interest rate forcefully to restore price stability.

Another way we use scenarios at the Bank is to explore different ways a shock could play out and how the outlook and our policy reaction could change as a result. We do this both in normal times and in times of heightened uncertainty.

I’ll give you an example. In April of this year, the war in the Middle East was about two months in and oil prices were around $100 per barrel. Our baseline assumption was that oil prices would decline to around $75 per barrel by mid-2027. Based on that path for oil prices, we projected inflation would return to the 2% target in early 2027.

But we couldn’t know how long the war would last or how long oil prices would stay elevated. So we used a scenario to ask: what if oil prices don’t come back down as assumed?

In the April high oil price scenario, inflation stays close to 3% for more than a year, and consecutive policy rate increases are needed to get inflation back to target.

Six months later, at the time of our October decision, the war had not ended and oil prices were still near $100 per barrel. Refinery margins were also above historical norms, adding to pressures on fuel prices. New US tariffs were creating fresh uncertainty, but the economy was doing better than we had expected.

Oil prices and inflation, meanwhile, had tracked the higher-for-longer April scenario more closely than the base case (Chart 3). In other words, the upside risk to inflation we had identified in April had largely materialized.

At the end of the day, we publish scenarios because we want people to understand the uncertainty we are facing, the risks we are watching and how we might react if they materialize.

Of course, that doesn’t mean we publish every scenario we analyze. Scenarios are most useful when we face extreme uncertainty or when they shed light on a material risk that is difficult to explain in words alone. Publishing too many at once could create confusion about which risks matter most and distract from the base-case forecast Governing Council has agreed is most likely.

Scenarios are particularly important in a shock-prone world. They let us test our base-case outlook against plausible alternatives and think through the consequences of being wrong. Publishing them, in turn, helps people understand how our policy response might change if circumstances change.

In this way, scenarios shift the focus from forecasting the future to preparing for it.

Accountability, credibility and trust

There is another benefit to being open about uncertainty: it keeps us accountable and builds credibility.

The Bank is operationally independent, so we can make monetary policy decisions free from political pressures. But we are still accountable to Canadians.11

Accountability starts with a clear, measurable objective. Ours is low and stable inflation, centred on the 2% target.12

Being accountable means ensuring Canadians have the information they need to judge our actions against that objective.

Openness also helps foster credibility. Credibility isn’t about always being right. That’s an impossible goal. It’s about being transparent about our thinking and showing that, no matter what happens, we remain focused on achieving our objective.

Publishing scenarios is one way we demonstrate our openness. Scenarios pull back the veil on our thinking, helping Canadians better understand our decisions. And they help build trust by showing that we’re being clear about what we know and what we don’t know.

Credibility matters for more than our reputation. When the public trusts us to keep inflation around 2%, their inflation expectations stay anchored to that target, which, in turn, makes monetary policy more effective.

Think about this in terms of your own business. If you expect or trust that the Bank will get inflation back to 2%, you are less likely to build higher inflation into your prices. That decision helps keep inflation in check and reduces the barriers to getting it back to target. It’s self-reinforcing.

Independence gives the Bank the space to act. Accountability means we explain our actions. And credibility helps those actions have the intended effect.

Conclusion

It’s time to wrap up.

Communications are essential for making monetary policy more effective. The better people understand our outlook and the risks around it, the better they can anticipate how we might react as conditions change.

This is particularly important in a world where shocks are more frequent and uncertainty is elevated. Scenarios help us illustrate how shocks or risks could affect the path for growth and inflation and how monetary policy could react. They help shift how policy signals are perceived: from what will happen to what could happen.

They also allow us to better communicate in times of extreme uncertainty. When certainty is in short supply, we don’t have to be paralyzed. And we certainly shouldn’t communicate less. Rather, we need to be open about what we know and candid about what we don’t. That matters for our credibility.

I would like to thank Jonathan Witmer and Chris Sutherland for their help in preparing this speech.

Related Information

November 18, 2026

Speech: Edmonton Chamber of Commerce

Scenario analysis and risk-management approach to monetary policy — Deputy Governor Toni Gravelle speaks before the Edmonton Chamber of Commerce (12:45 (ET) approx.).

  1. 1. A. Greenspan, “Since I've become a central banker, I've...” Los Angeles Times Archives, September 27, 1987.[←]
  2. 2. C. Rogers, “The Bank of Canada: A matter of trust” (speech to Women in Capital Markets, Toronto, Ontario, May 3, 2022).[←]
  3. 3. Reaction function refers to a central bank’s systematic policy reaction to economic developments (or shocks) over the short and longer term. There is no exact formula for the Bank of Canada’s reaction function because it depends on the specific context and includes Governing Council’s judgment of how risk and uncertainties will evolve.[←]
  4. 4. Before this change, the Bank tended to adjust the policy interest rate the day after Federal Reserve decisions. As a result, markets had become focused on US data for clues about Canadian monetary policy. Fixed announcement dates helped shift the focus back to economic conditions in Canada, which played an important role in our decision making. See N. Parent, P. Munro and R. Parker, “An Evaluation of Fixed Announcement Dates,” Bank of Canada Review (Autumn 2003): 3–11, and B. DeBruin Martos, R. Sekkel, H. Stern and X. Zhang, “Is anyone surprised? The high-frequency impact of US and domestic macroeconomic data announcements on Canadian asset prices,” Bank of Canada Staff Analytical Note No. 2025-10 (March 2025).[←]
  5. 5. See M. Jain, W. Muiruri, J. Witmer, S. Kozicki and J. Harrison, “Summaries of Central Bank Policy Deliberations: A Canadian Context,” Bank of Canada Staff Discussion Paper No. 2023-2 (January 2023). For an international perspective, see S. Hansen, M. McMahon and A. Prat, “Transparency and Deliberation Within the FOMC: A Computational Linguistics Approach,” Quarterly Journal of Economics 133, no. 2 (2018): 801–870.[←]
  6. 6. The Bank has used extraordinary forward guidance only twice, during the global financial crisis and the pandemic. In both cases, the forward guidance added monetary stimulus as intended. See C. S. Sutherland, “Forward guidance and expectation formation: A narrative approach,” Journal of Applied Econometrics 38, no. 2 (2023): 222–241, and C. S. Sutherland, “Extraordinary Forward Guidance in Canada During the Pandemic,” Bank of Canada Staff Analytical Paper No. 2026-1.[←]
  7. 7. See C. Fay and T. Gravelle, “Has the Inclusion of Forward-Looking Statements in Monetary Policy Communications made the Bank of Canada More Transparent?” Bank of Canada Staff Discussion Paper No. 2010-15. Fay and Gravelle find that during periods when the Bank provided forward guidance statements in press releases, market participants were less responsive to new macroeconomic data releases than they were in times when forward guidance was not provided.[←]
  8. 8. See S. S. Poloz, “Let Me Be Clear: From Transparency to Trust and Understanding” (speech to the Greater Victoria Chamber of Commerce, Victoria, British Columbia, June 27, 2018) and K. Warsh, “In Our Time” (speech to the Jackson Hole Economic Policy Symposium, Jackson Hole, Wyoming, August 28, 2026).[←]
  9. 9. Fan charts allow a central bank to make statements such as there’s a 50% chance that inflation will be between 2% and 2.5% a year from now. The Bank used fan charts for a period starting shortly after the global financial crisis but no longer does so. With the rise of scenarios, fan charts have fallen out of favour among many central banks.[←]
  10. 10. See S. Kozicki and J. Vardy, “Communicating Uncertainty in Monetary Policy,” Bank of Canada Staff Discussion Paper No. 2017-14 (November 2017).[←]
  11. 11. The Governor and the Senior Deputy Governor regularly appear before committees of the House of Commons and Senate. They also hold press conferences after every interest rate decision. Members of Governing Council give speeches explaining policy, meet with business and community groups and travel across the country to speak with Canadians.[←]
  12. 12. Every five years, the Bank and the federal government jointly review and renew the Bank’s monetary policy framework. The 2% target for inflation was renewed on November 5, 2026, with the latest agreement running until December 31, 2031. See Bank of Canada, “Joint Statement of the Government of Canada and the Bank of Canada on the Renewal of the Monetary Policy Framework” (press release, Ottawa, Ontario, November 2026).[←]